
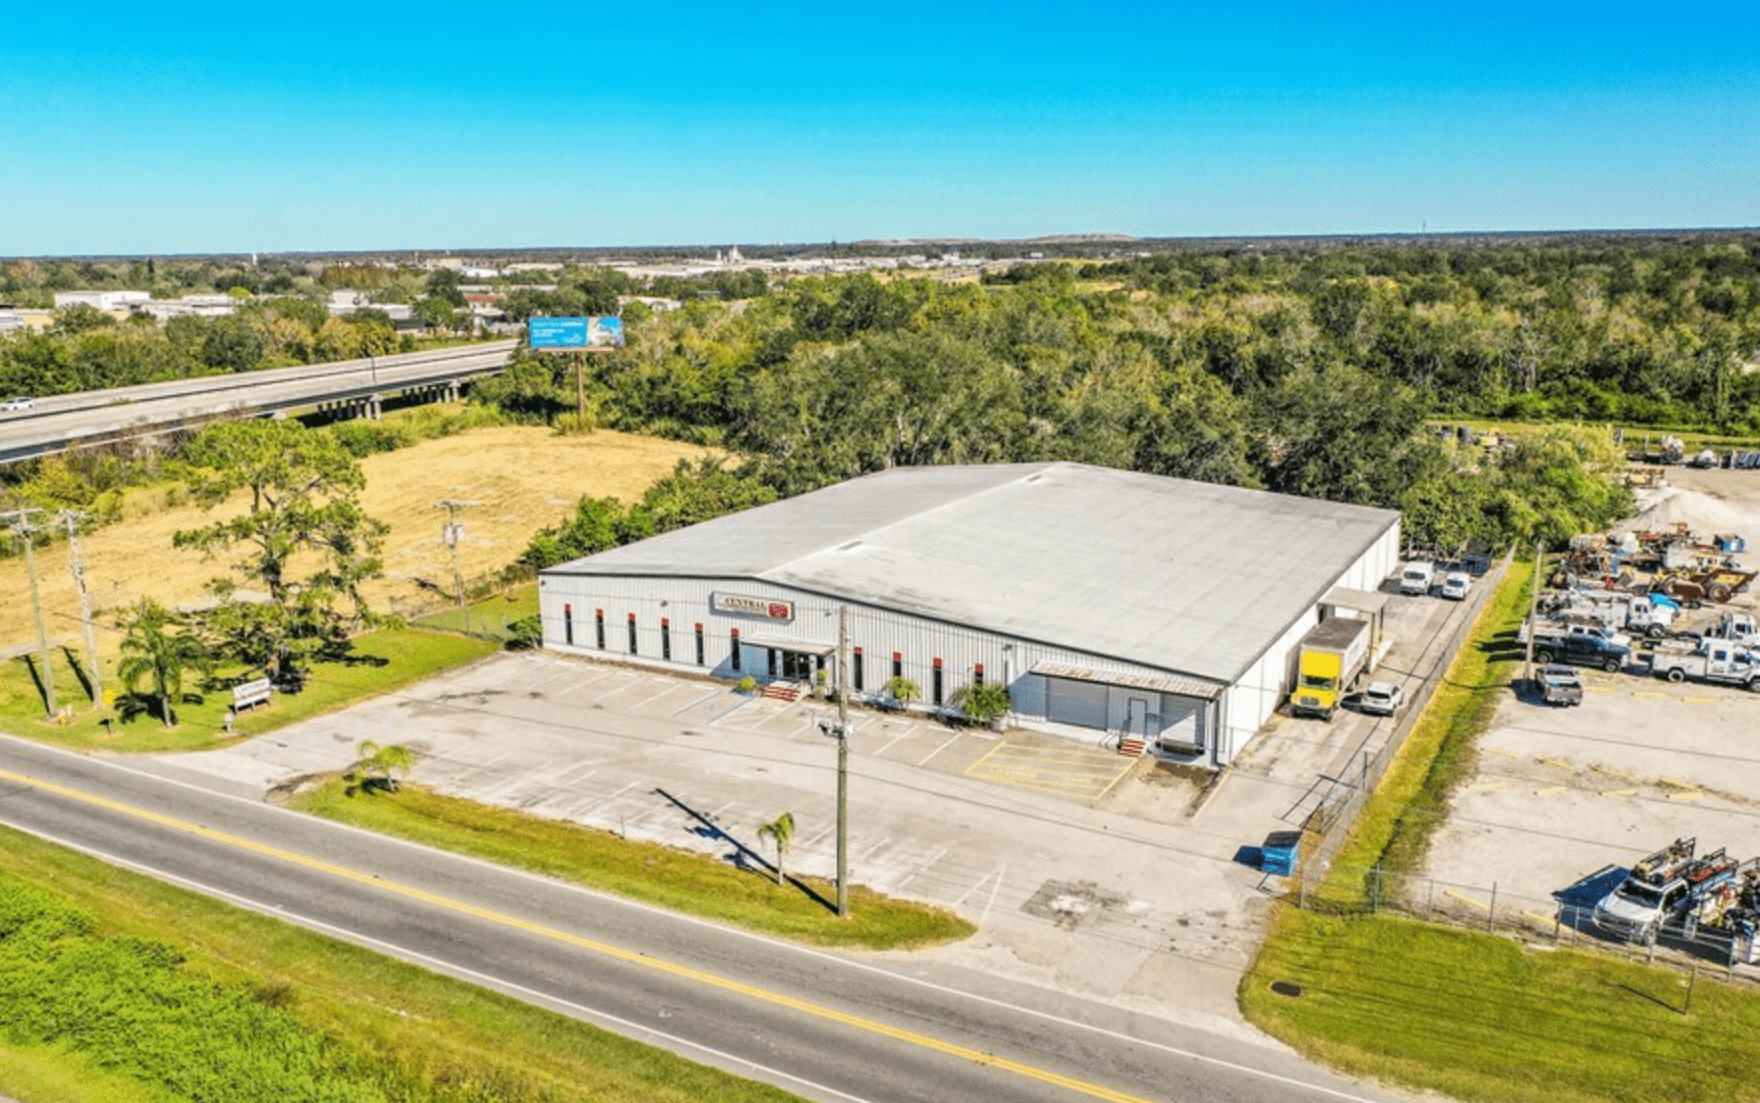
Single-tenant industrial is a different animal from multi-tenant. The whole value of the building rides on one lease. One tenant. One relationship. That makes the underwriting pretty simple but the risk profile is totally different.
-
Tenant Rating: How creditworthy is your tenant? National company, regional, or local? Independently verified business metrics or second-hand reports? -
Lease Term Remaining: How many years are left? Anything under 2 years is short-term risk. -
Renewal Probability: Has the tenant indicated renewal intent? Are there alternatives if they leave? -
Building Specialization: If the tenant leaves, how easily can the space be converted for other uses?
When the lease is strong
If you’ve got a creditworthy tenant on a 5-10 year NNN lease, congratulations. That’s the easiest building to sell in commercial real estate. Buyers love predictable income with minimal management. Cap rates on these deals are tight. I’m seeing 6-7% in the Carolinas for decent single-tenant industrial with term remaining.
What Buyers Love in Single-Tenant
- National or regional tenant with investment-grade credit
- 5+ year lease remaining with renewal options
- NNN lease structure (tenant bears all operating expense risk)
- Flexible building specs that work for multiple tenant types
- Strong lease escalations keeping pace with inflation
What Tanks Single-Tenant Value
- Local tenant with limited financial history or credit
- Lease expiring in 1-2 years with no renewal commitment
- Gross lease with landlord bearing tax/insurance risk
- Specialized building customized for current tenant (custom equipment, layout)
- Tenant financial stress or industry headwinds
The key factors: how much lease term is left, what the rent bumps look like, and whether the tenant has renewal options. A building with 8 years of term remaining is worth a lot more than one with 18 months left. Because at 18 months, you’re basically buying a soon-to-be-vacant building.
When the tenant is leaving
This is where it gets tricky. If your tenant has told you they’re not renewing, or the lease expires soon and you’re not confident they’ll stay, the building gets priced differently. Now I’m looking at it as a vacant building. What will it cost to find a new tenant? How long will it sit empty? What TI will the next tenant need?
I bought a single-tenant building in Spartanburg where the tenant had six months left. Owner knew they weren’t renewing. We priced it based on the vacant scenario plus a small credit for the remaining six months of rent. Fair for both sides.
Related: Castle Hayne and the North Wilmington Industrial Corridor
The owner-occupied angle
A lot of single-tenant industrial buildings in the Carolinas are owner-occupied. The owner runs their business out of it. When they’re ready to retire or sell the business, the real estate becomes a separate question.
Sometimes the business buyer wants the building too. Sometimes they don’t. If the building is going to be vacant after the business sale, I can step in and buy the real estate directly. I’ve done this a few times and it works well because the timeline is usually known well in advance.
Seller takeaway
Single-tenant buildings are only as strong as the tenant and lease. If you own industrial with a lease expiration coming up, call Roth Capital at 704-600-3839. Let’s talk about your tenant’s renewal odds and what your property will be worth after the lease ends.
If you’ve got a single-tenant industrial building in Greensboro or anywhere in the Carolinas, I’d be happy to look at it. The value depends heavily on the lease situation, so the sooner we talk the better. 704-600-3839.
Ready to explore your options?
Tell us about your property. We will follow up within one business day.



Recent Comments